The Annual Household Expense Review: A Family Finance Checklist
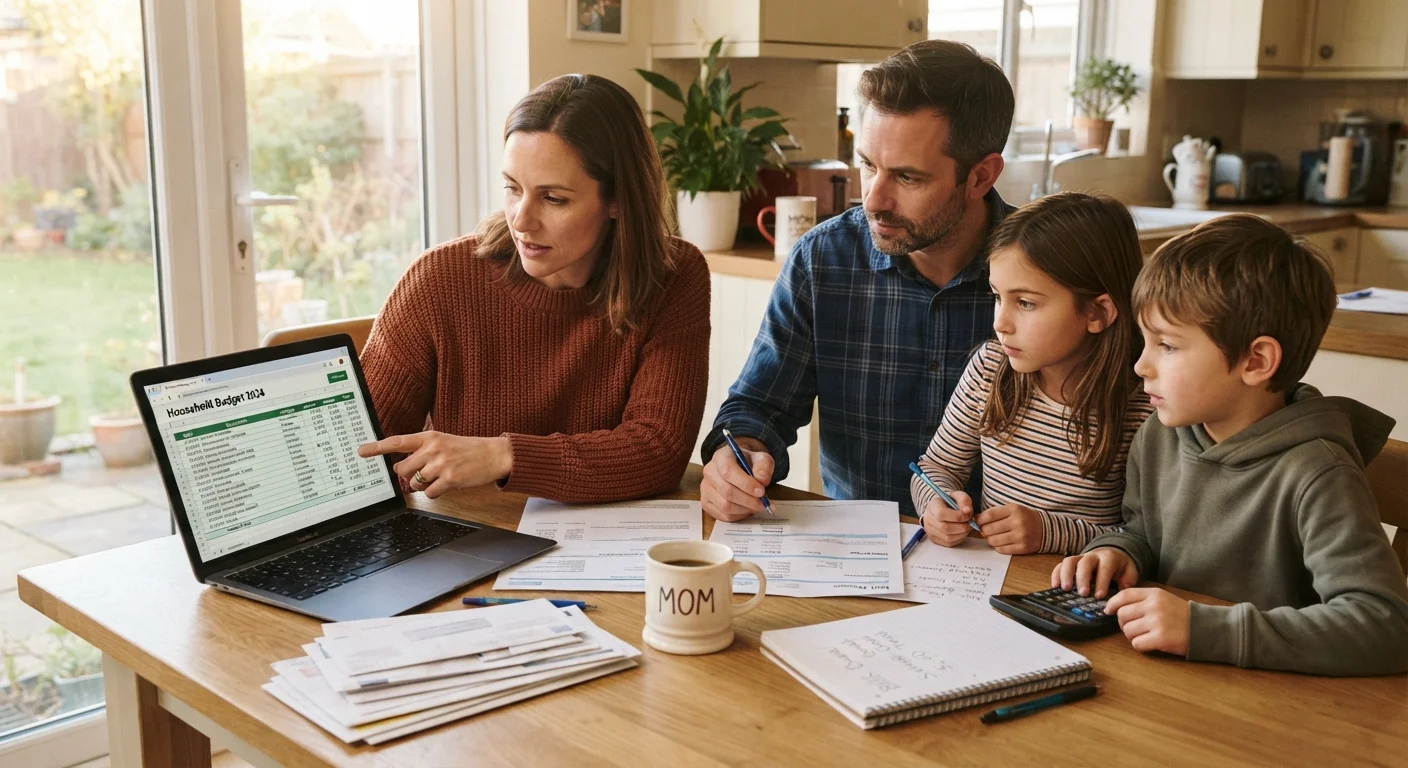
Photo credit: featuredbuzz.com
In this article
A structured checklist to help families review recurring costs, identify waste, and realign spending with their actual priorities once a year.
Key Takeaways
- Most households have at least two or three recurring charges they no longer use or need.
- Reviewing insurance, utilities, and subscriptions once a year can surface meaningful savings.
- A structured checklist keeps the review focused and prevents important categories from being skipped.
- Small adjustments across several categories often add up to more than one large cut.
- The goal is to align spending with what your family actually values, not to cut everything.
Why this review is worth your time
Household costs tend to grow quietly. A streaming service added during a free trial, a gym membership nobody uses anymore, an insurance policy that hasn't been compared in three years. None of these feel urgent to address until you sit down and look at the full picture.
A once-a-year review gives you that picture. It is not about finding fault in your spending habits. It is about confirming that the money leaving your account every month is actually going somewhere your family cares about. If it is, great. If it isn't, you now know where to start.
For families also planning travel, it helps to connect this review to broader financial goals. When you can see where recurring costs are inflated, you can redirect that money toward priorities. Our family vacation budget walkthrough is a useful companion once you have completed this audit and know what you have to work with.
Set aside an hour or two, gather your bank and credit card statements from the last three months, and work through the checklist below. You do not need to resolve everything in one sitting. Identifying the issues is the first step.
What you will need before you start
Having the right documents in front of you makes the review much faster. Pull these together before you begin.
Bank and credit card statements (last 3 months)
The primary source for identifying all recurring and discretionary charges.
Current insurance policy documents
Needed to compare coverage levels and premiums during the insurance section of the review.
Spreadsheet or notepad
Used to record findings, flag items for action, and total up potential savings.
Utility bills (last 12 months)
Allows year-over-year comparison to catch unusual increases in energy, water, or internet costs.
Password manager or email inbox search
Helps surface subscription confirmations and renewal notices you may have forgotten.
The full household expense checklist
Work through each group in order. Mark items as done, flag ones that need a follow-up call or comparison, and note any charges you cannot identify. Anything unrecognized should be verified with your bank before you do anything else.
Subscriptions are one of the fastest areas to find waste. If you want a deeper process specifically for recurring digital services, the household subscription audit guide walks through that category in more detail.
Subscriptions and memberships
Insurance
Utilities and home services
Food and household consumables
Entertainment and recreation
Debt and financial costs
Once you have worked through the full list, total up the monthly charges you have flagged for cancellation or renegotiation. Even modest changes across several categories can amount to several hundred dollars over a year. For a structured way to manage what remains, the envelope budget system is worth looking at as a next step.
What to do with what you find
A completed checklist with flags and notes is only useful if you act on it. Group your findings into three buckets: cancel now, renegotiate or shop around, and monitor for the next 90 days.
For anything in the renegotiate column, a short call to your provider is often enough to get a lower rate, particularly for insurance, internet, and some utility plans. Providers are generally more willing to work with long-standing customers than most people expect.
If the review surfaces a pattern of small daily or weekly spending that adds up, the article on habits that quietly drain a family budget covers those in practical terms. And if one goal coming out of this review is building a financial cushion, the family emergency fund guide is a straightforward place to start.
Put a calendar reminder for twelve months from now. The review is most useful when it becomes a regular habit rather than a one-time fix.
Author
Frugal Family Living Editorial Team
Frugal Family Living Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →