Building a Family Emergency Fund from Near Zero
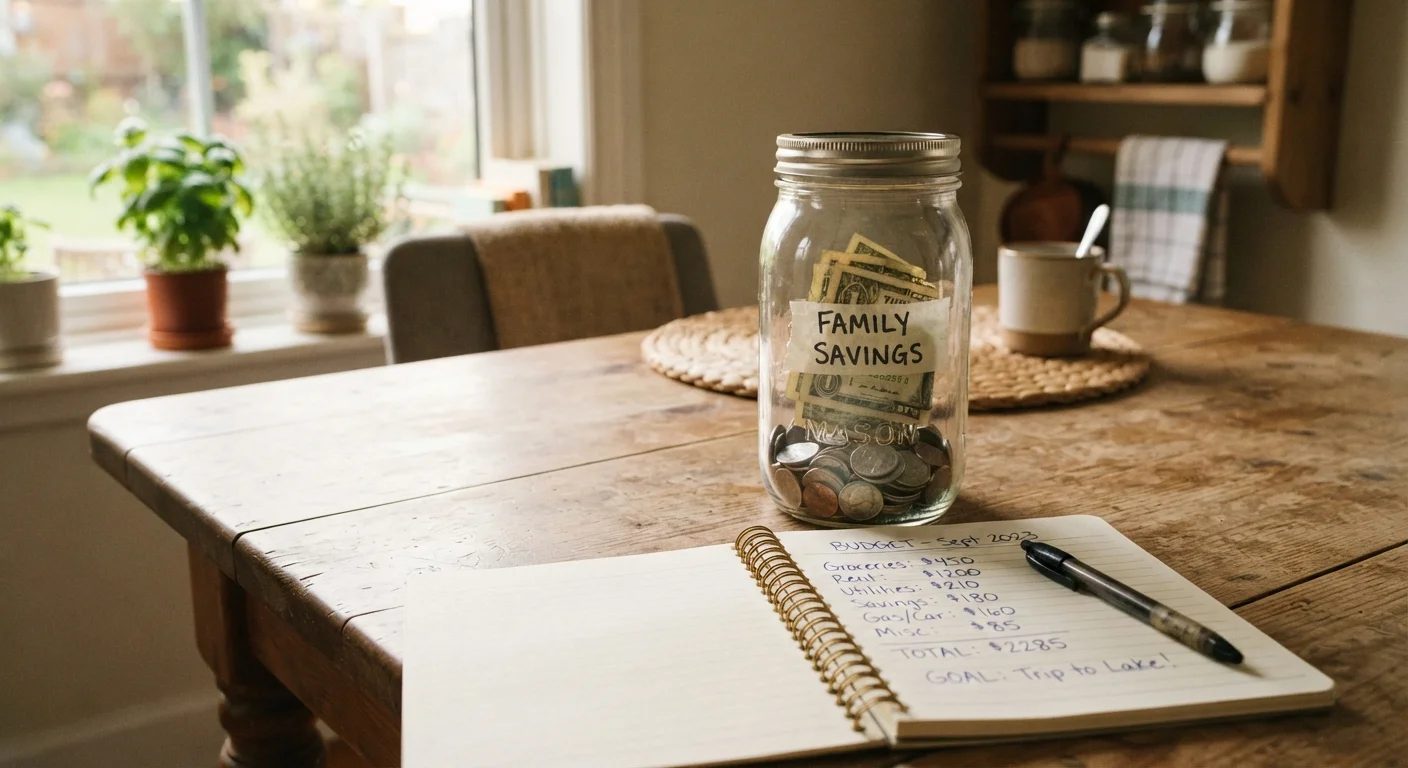
Photo credit: featuredbuzz.com
In this article
A beginner-friendly walkthrough for households that want a financial cushion but aren't sure where to start or how much to aim for.
Key Takeaways
- A $500 starter goal is more achievable than three months of expenses and still covers most emergencies.
- Cutting one or two recurring costs often frees enough cash to begin saving immediately.
- A separate savings account, away from checking, reduces the temptation to spend the fund.
- Automatic transfers on payday remove willpower from the equation and build consistency.
- Small, steady contributions compound over time more reliably than sporadic large deposits.
Why an emergency fund matters more than most people realize
An emergency fund is a cash reserve set aside specifically for unplanned expenses: a car repair, a medical bill, a broken furnace in January. Without one, most families cover these costs with a credit card or a personal loan, which adds interest on top of the original problem.
The financial pressure this creates is real. A household that dips into debt every time something goes wrong has a harder time getting ahead, because a portion of each paycheck goes toward paying off the last crisis rather than building stability. A cash cushion, even a modest one, breaks that cycle.
The goal here is not to reach some ideal number before anything counts. A fund that can cover a $400 car repair without touching a credit card is already doing its job.
Emergency fund
A dedicated savings reserve used only for unexpected, necessary expenses. It is kept separate from everyday spending money.
Essential expenses
The costs a household cannot skip without serious consequence, such as housing, utilities, food, and transportation.
Automatic transfer
A scheduled instruction to your bank to move a fixed amount from one account to another on a set date, without any manual action needed.
FDIC / NCUA insured
A federal guarantee that protects deposited money up to $250,000 per depositor if the bank or credit union fails. Most standard savings accounts carry this protection.
Liquid savings
Money you can access quickly, usually within a few days, without selling an investment or paying a penalty.
How much should a family actually save?
Personal finance guidance often suggests three to six months of living expenses. For a family spending $4,000 a month on essentials, that means $12,000 to $24,000. That number can feel paralyzing when you are starting from zero.
A more practical approach is to set a first target of $500 to $1,000. According to the Federal Reserve's Survey of Household Economics and Decisionmaking, a significant share of American adults say they could not cover a $400 unexpected expense without borrowing. Getting to $500 in savings already puts a household ahead of where many others are.
After hitting that first milestone, the next target could be one month of essential expenses, meaning rent or mortgage, utilities, groceries, and transportation. From there, you can grow the fund over time. The point is to build in stages rather than waiting until a large amount feels reachable.
If you want a clearer picture of what your household spends each month, a structured review can help. The annual household expense review covers exactly how to do that.
Finding money to put away when the budget feels tight
Most families do not have obvious slack in their budget, but small adjustments across several areas can add up. The goal is to find a consistent monthly amount to transfer to savings, even if it starts at $15 or $20.
- Review recurring subscriptions: streaming services, apps, and memberships you no longer use regularly are often the quickest cuts.
- Check your grocery spending for patterns. Switching a few items to store-brand equivalents or planning meals around weekly sales can reduce costs without changing what your family eats.
- Look at utility habits. Adjusting the thermostat by a few degrees, running the dishwasher at off-peak hours, and fixing dripping faucets are practical steps that lower monthly bills over time.
- Consider entertainment costs. Free activities can replace some paid outings without the family feeling the difference. The zero-cost family day guide offers a practical framework for doing exactly that.
If your budget feels like there is genuinely nothing left, a structured method like zero-based budgeting or the envelope system can help you see where money is actually going and find the gaps.
Start with one cut, not ten
Trying to overhaul your entire budget at once is exhausting and rarely sticks. Pick one expense to reduce this week, move that amount to savings, and hold it there for a month before making the next change. Small wins build the habit more reliably than a full reset.
Where to keep the fund
The account you choose matters more than most people expect. Keeping emergency savings in your regular checking account makes it too easy to spend. A separate savings account creates a small mental and logistical barrier that helps the money stay put.
Look for an account that is federally insured (FDIC for banks, NCUA for credit unions), charges no monthly fees, and allows you to transfer money back to checking within one to two business days when you genuinely need it. Many online savings accounts pay more interest than traditional branch accounts, though interest rates vary and change over time.
Avoid putting emergency savings into investment accounts such as brokerage accounts or retirement funds. The value of those accounts can drop right when you need the money most, and early withdrawal from retirement accounts often carries taxes and penalties.
Making saving automatic and keeping momentum
The most reliable way to build an emergency fund is to remove the decision from the process entirely. Most banks allow you to set up an automatic transfer from checking to savings on a date you choose, such as the day after payday. Even $25 a transfer adds up to $600 over a year if you are paid twice a month.
Once the transfer is set, treat it like any other fixed bill. It goes out, and what remains is what you have to spend. Over time, as income grows or expenses drop, you can increase the transfer amount without restructuring anything else.
Tracking progress visually, whether in a notebook, a spreadsheet, or a banking app, gives the process a concrete feel. Seeing the balance climb, even slowly, reinforces the habit. When the fund covers its first real emergency and you do not have to use a credit card, that moment tends to strengthen the motivation to keep going.
Building an emergency fund from near zero takes patience, but consistency across small amounts is what gets households there. The amount you save each month matters less than whether you save at all.
Frequently Asked Questions
Author
Frugal Family Living Editorial Team
Frugal Family Living Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →