Zero-Based Budgeting Explained for Everyday Families
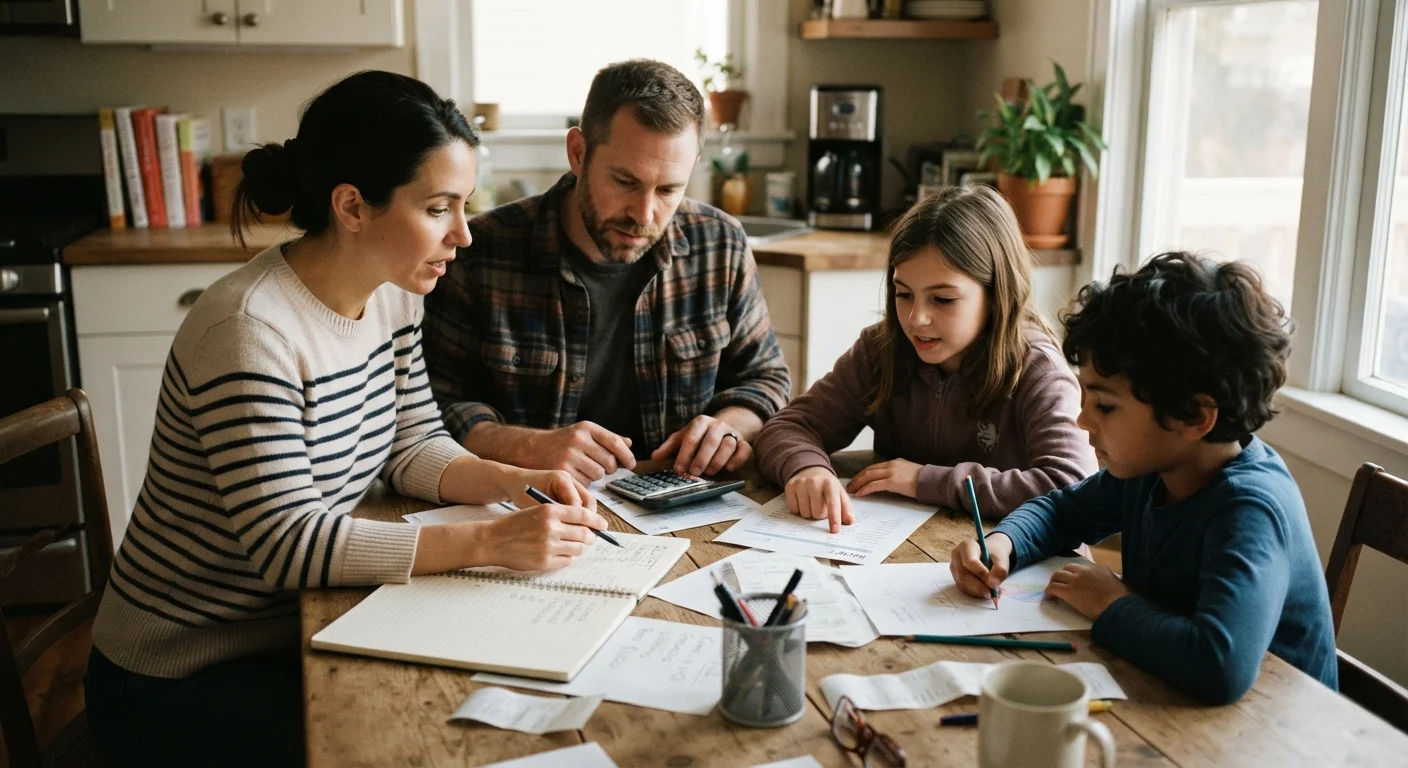
Photo credit: featuredbuzz.com
In this article
What zero-based budgeting actually means, how it differs from tracking spending after the fact, and whether it suits a busy household.
Key Takeaways
- Every dollar gets assigned a purpose before the month begins, leaving no untracked money.
- Zero-based budgeting differs from expense tracking because it is forward-looking, not backward-looking.
- Irregular income households can still use this method by budgeting from the lowest expected monthly amount.
- The method works best when the whole household agrees on the spending categories.
- It takes two to three months before the category amounts feel accurate for a real family.
What zero-based budgeting actually means
The name sounds complicated, but the idea is straightforward. You take your total monthly income and subtract planned spending in every category until nothing is left unaccounted for. Rent, groceries, utilities, kids' activities, savings, and even small items like haircuts all get their own line. Income minus every assigned category equals zero.
That zero does not mean your bank account hits zero. It means you have made a deliberate choice about every dollar before the month starts, including moving money into savings or an emergency fund. Those count as assignments too. If you want to build a financial cushion, see the beginner's guide to building a family emergency fund for a practical starting point.
The contrast with ordinary expense tracking matters here. Tracking tells you where money went after the fact. Zero-based budgeting tells money where to go before it gets there. That shift in timing changes how much control a household actually has.
How to build one for your household
Start by writing down your household's total take-home income for the month. Use the actual amount that lands in your accounts, after taxes and deductions.
Next, list every spending category your family has. Fixed expenses come first: mortgage or rent, car payments, insurance premiums, and utilities with predictable amounts. Then move to variable necessities: groceries, gas, and medical copays. After those, list the categories that are easy to forget, such as school supplies, birthday gifts, pet costs, and clothing. Finally, assign amounts to savings, any debt payments, and anything you are setting aside for a future goal like a vacation. The step-by-step vacation budget walkthrough is useful here if travel is one of your family's goals.
Add everything up. If the total is less than your income, assign the remaining dollars somewhere specific. If the total exceeds your income, trim categories until the numbers balance.
Leave a small 'miscellaneous' category
Most families benefit from keeping a small buffer category, around $20 to $50, labeled 'miscellaneous' or 'forgot to budget.' This covers the parking fee, the school bake sale, or the random household item that did not fit anywhere else. It is still assigned money, which keeps the budget balanced, and it prevents the whole plan from unraveling over a small unexpected cost.
The first month, most families forget at least two or three categories. Common ones include streaming subscriptions, school fees, vehicle registration, and seasonal costs like holiday spending. After running the budget for a few months, the category list becomes more complete on its own.
Where families run into trouble and how to handle it
Variable income is the most common sticking point. If one or both adults in the household have hours that change, freelance work, or seasonal pay, the income number at the top of the budget is uncertain. The practical fix is to budget from the lowest amount you reliably expect. When the actual paycheck is higher, assign those extra dollars to a category before spending them. That prevents the extra money from disappearing without a clear purpose.
Another problem is categories set too tight in the first month. Groceries for a family of four almost always cost more than people initially estimate, especially when snacks, school lunches, and household supplies are included in the same store run. Give yourself permission to adjust the numbers mid-month in the first couple of months. That is not failure; that is calibration.
A third issue is one partner doing all the budgeting while the other is unaware of the category limits. This creates friction at the checkout line and resentment about money. Even a 15-minute conversation at the start of each month, where both adults see the categories and amounts, reduces this problem significantly. If overspending in small daily habits is a recurring issue, the article on spending habits that quietly drain a budget covers where that money typically goes.
Whether this method fits your household
Zero-based budgeting works well for households that feel like money disappears each month without a clear reason, want to save for something specific, or are trying to pay down debt more intentionally. It requires some front-end effort and a willingness to revisit the numbers monthly.
It is less suited for households where income is so unstable that any forward projection feels meaningless, or where one adult refuses to participate. A budget that only one partner follows will break down quickly in a shared household.
For families who find digital tools easier than paper, a simple spreadsheet covers everything this method needs. For those who prefer a physical system, the envelope budgeting method uses the same assign-before-spending logic with cash and labeled envelopes instead of a screen.
The method does not require perfection. A month where two categories go over budget is still more controlled than a month with no plan at all.
Frequently Asked Questions
Author
Frugal Family Living Editorial Team
Frugal Family Living Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View all articles →